Advantages and disadvantages at a glance
Advantages
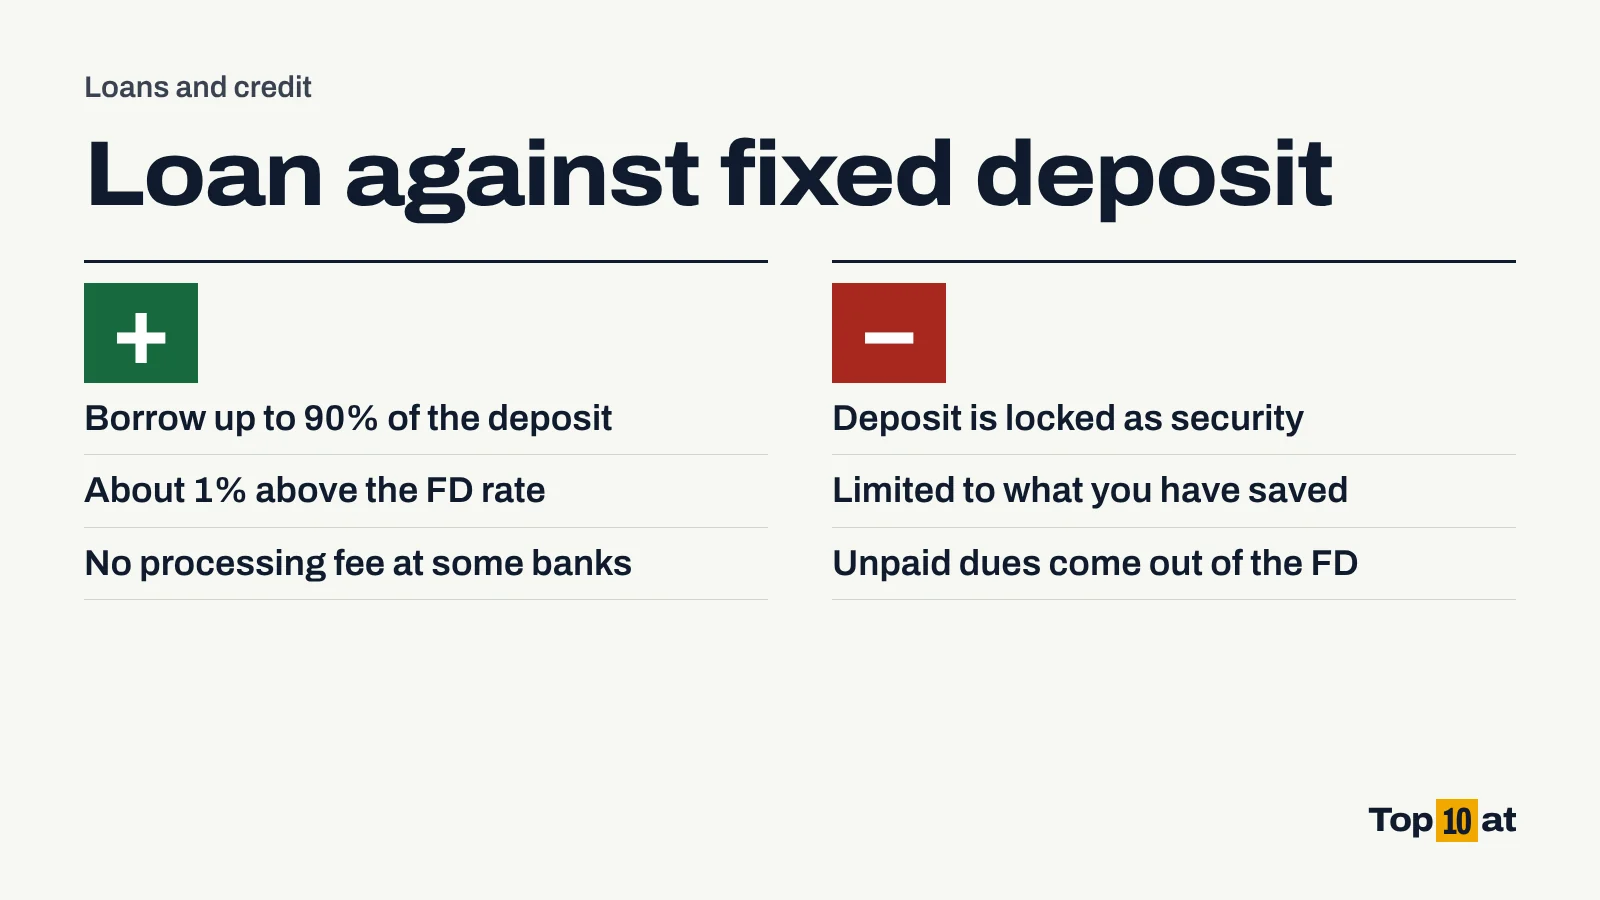
- You can borrow up to about 90% of the deposit's value
- The interest rate is close to the deposit rate
- Some banks charge no processing fee and no prepayment penalty
- The deposit stays in place instead of being closed early
- You can borrow as a loan or as an overdraft
- It can be arranged online at some banks
Disadvantages
- The loan is capped by the size of your deposit
- The deposit is under lien and cannot be withdrawn
- Anything unpaid at maturity is taken from the deposit
- Not every type of deposit qualifies
- You are paying to borrow your own money
- Online access can be limited to single account holders
Advantages explained
A high share of the deposit
Because the bank already holds your money, it can lend most of it back. State Bank of India lends up to 90% of the value of a time deposit, keeping a margin of at least 10%.
A low interest rate
SBI charges 1% above the rate on the deposit itself, calculated on the daily reducing balance. The deposit goes on earning its own rate, so the net cost of borrowing is roughly that one percentage point for as long as the loan is outstanding.
No fees at some banks
SBI states that it charges no processing fee and no prepayment penalty on this loan. You can repay whenever you have the money.
The deposit is not broken
The alternative to borrowing is usually to close the deposit early. That ends the deposit and its interest rate. With a loan, the deposit continues to maturity.
Loan or overdraft
SBI offers both forms. A demand loan gives you a fixed sum. An overdraft gives you a limit to draw on when needed, and interest is charged only on what you actually use.
Available online
At SBI, a customer who holds a deposit in a single name can set up an overdraft against it through internet banking or the YONO app, up to ₹5 crore.
Disadvantages explained
You can borrow only against what you have
The limit is a percentage of the deposit. A ₹2 lakh deposit supports a loan of at most ₹1.8 lakh at a 90% limit. This is a way to get temporary access to your savings. It does not give you new money.
The deposit is locked
The bank marks a lien on the deposit, which means you cannot withdraw or close it while the loan is outstanding.
Unpaid dues are recovered from the deposit
At SBI, a demand loan that is still unpaid when the deposit matures is settled out of the maturity amount. If you do not repay, you receive less at the end.
Some deposits do not qualify
SBI's online facility is not available against tax-saving deposits, recurring deposits or certain other deposit types, and it lends a lower share, 75%, against one category of term deposit online. Check what your own deposit allows.
You are paying a spread on your own savings
Borrowing against a deposit costs about 1% a year more than the deposit earns. For a few months that is a small price. Over several years it adds up, and it may be simpler to use the savings directly.
Joint accounts need a branch visit
At SBI, joint deposit holders have to apply at a branch. Only single holders can use the online route.
What the terms look like in practice
| Term | State Bank of India, as published |
|---|---|
| Loan amount | Up to 90% of the deposit's value |
| Margin kept by the bank | At least 10%; 15% for demand loans longer than 5 years |
| Interest rate | 1% above the rate on the deposit, on the daily reducing balance |
| Processing charges | None |
| Prepayment penalty | None |
| Demand loan period | Until the deposit matures, or 120 months, whichever is earlier |
| Overdraft period | Up to 5 years, or until the deposit matures, whichever is earlier |
| Online limit | Up to ₹5 crore as an overdraft, for single account holders |
| Security | Lien on the time deposit |
Who it suits and who it does not
It can make sense if
- You need money for a short period and expect to repay soon
- Your deposit is earning a good rate that you do not want to lose
- You want a low-cost overdraft to fall back on
Think again if
- You need more than your deposit is worth
- You are unlikely to repay before the deposit matures
- The need is long-term, in which case using the savings may cost less
Loan against the deposit, or close the deposit?
Work out both before deciding.
- Borrowing costs the spread, about 1% a year at SBI, for as long as you owe the money. The deposit keeps its rate.
- Closing early has no interest cost, but you give up the remaining term at the deposit's rate, and banks commonly pay a lower rate on deposits closed before maturity. Ask your bank what it would pay.
As a rule of thumb, the shorter the period you need the money for, and the longer the deposit still has to run, the more a loan makes sense.
This is general information
Loan terms differ between lenders and change over time. The example terms on this page are one bank's published terms on the date shown and are there to illustrate how the product works. They are not a recommendation of that bank or of the product. Check current terms with the lender, and take advice suited to your own finances before you borrow.
Frequently asked questions
How much loan can I get against a fixed deposit?
A percentage of the deposit's value. State Bank of India lends up to 90%.
What is the interest rate on a loan against FD?
It is set as a margin above the deposit's own rate. At State Bank of India it is 1% above the rate on the deposit.
Can I withdraw my FD while there is a loan against it?
No. The bank marks a lien on the deposit, and it cannot be withdrawn until the loan is repaid.
What happens if I do not repay a loan against FD?
The bank recovers what you owe from the deposit. At State Bank of India an unpaid demand loan is settled from the proceeds when the deposit matures.
Can I get a loan against a tax-saving fixed deposit?
State Bank of India does not offer its online loan facility against tax-saving deposits. Ask your bank about its own rule.
Sources
- Loan against time deposit, State Bank of India. sbi.bank.in. Accessed 11 October 2026. The example terms: amount, margin, interest, charges, repayment and online availability.